All sales of goods and services in Taiwan, as well as the importation of goods into Taiwan, are subject to VAT. Businesses are required to issue Government Uniform Invoices (GUI) to their customers at the time goods are sold or services are rendered.
Output VAT is the tax that customers pay on sales transactions; input VAT is the tax that businesses pay on purchase transactions. The amount of VAT payable or overpaid by a company is the difference between the two in a given tax period.
A company, regardless of whether it has sales, must file a bimonthly VAT return with the competent tax authority no later than the fifteenth day of the following period. For example, the VAT filing due date for the January–February period is March 15, and the due date for March–April is May 15.
Government Uniform Invoice (GUI) overview
Except for a few specifically exempt businesses, all companies are required to issue GUIs for their sales of goods or services. Private or company-designed invoices are not permitted as substitutes.
- If the purchaser is a business entity, the VAT must be stated separately from the sales amount on the GUI.
- If the purchaser is not a business entity, the VAT does not need to be itemized.
- A GUI issued by a non-VAT business entity only needs to state the sales amount.
The Uniform Invoice system is managed by the Taiwanese tax authority, which assigns unique invoice numbers for every GUI to track company revenues. These invoice numbers must be used within a two-month period.
The five types of Government Uniform Invoice
(1) Triplicate GUI. Invoices issued to business entities. Three copies are required for tracking and auditing purposes:
| Copy | Held by | Purpose |
|---|---|---|
| First (retention copy) | Issuer | Issuer’s own record |
| Second (deduction copy) | Purchaser | Tax deduction or reduction declarations under the VAT Act |
| Third (receipt copy) | Purchaser | Accounting voucher |
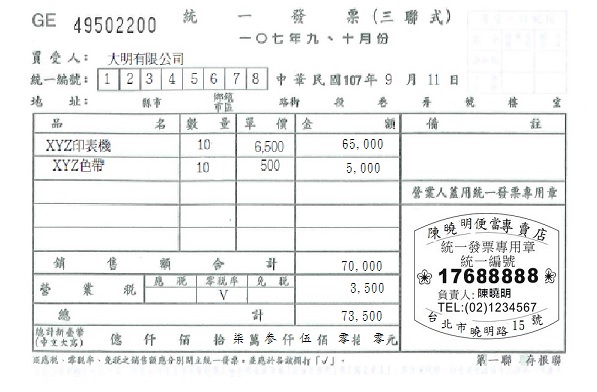
Sample triplicate GUI (retention copy). The seller’s GUI stamp sits in the lower right; VAT is shown separately from the sales amount.
(2) Duplicate GUI. Issued to individual consumers or foreign companies. Only two copies: the retention copy kept by the issuer, and the receipt copy given to the purchaser as proof of purchase. If you export goods, or provide services to a foreign company that are used outside Taiwan, you are not legally required to issue a GUI (Article 4, Item 33 of the Uniform Invoice Use Regulations). We still recommend issuing a duplicate zero-rated GUI so the revenue is properly recorded. Services provided to a foreign company but used in Taiwan do not count as exports and still need a GUI.
(3) Computerized register GUI. Issued when a business uses a cash register or POS system to record sales, printed automatically and usually appearing as receipts. Starting January 1, 2021, computerized register GUIs were officially discontinued in Taiwan. The National Taxation Bureaus no longer allocate serial numbers for this type. Businesses previously using them have had to switch to other formats, such as electronic GUIs or cash register GUIs.
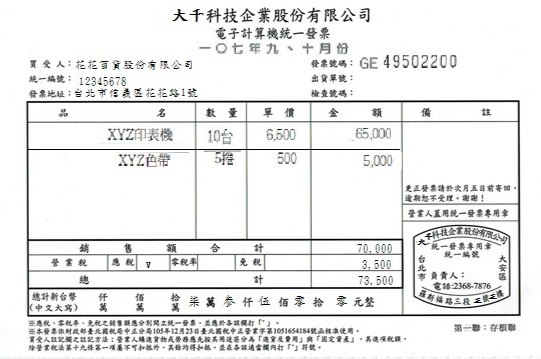
Sample computerized register GUI, no longer issued since 2021.
(4) Cash register GUI. Receipts printed directly from a government-approved cash register, commonly used by small-scale retailers where a simplified invoicing system is sufficient. Unlike computerized register GUIs (linked to advanced POS systems), these are issued through basic cash registers pre-registered with the tax authority. Each receipt still contains a unique government-assigned invoice number, and they are eligible for the uniform invoice lottery.
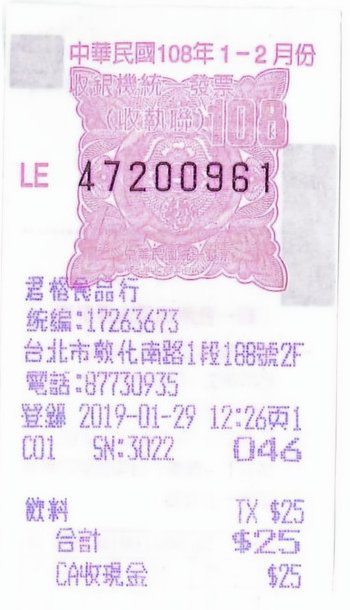
Sample cash register GUI (receipt copy).
(5) Electronic GUI. The digital version of the GUI, and now the mainstream invoice type in Taiwan. Businesses must generate three digital files for each e-invoice: a retention file kept by the issuer, a receipt file provided to the purchaser, and a certification file that the issuer must upload to the Ministry of Finance e-invoice platform within 2 days (sales to consumers) or 7 days (sales to businesses), counted from the day after issue. Since 2025, late or inaccurate uploads can be fined NT$1,500–15,000, and fined again if not corrected. Commonly used in e-commerce, retail chains, and by digital service providers. Customers can check e-invoice records on the Ministry of Finance e-invoice platform. For returns and allowances on an e-invoice, the seller issues the electronic allowance certificate and uploads it to the platform within the same deadlines.
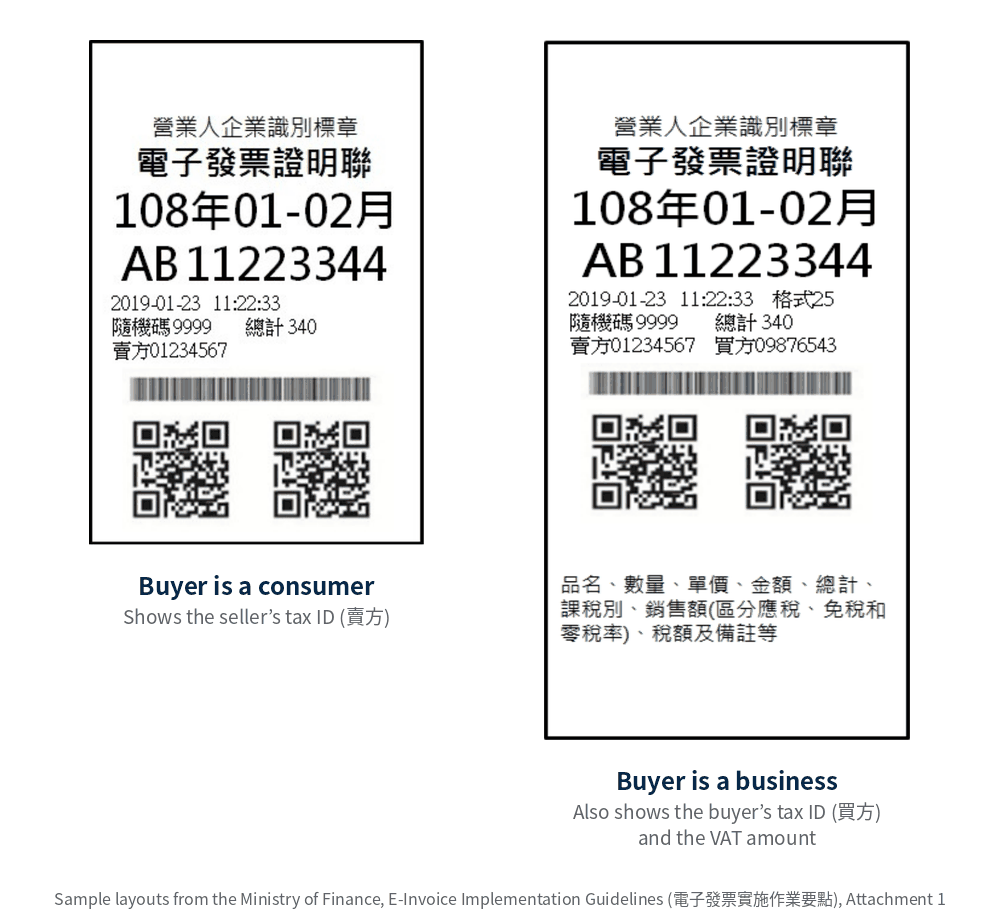
What customers receive: the printed e-invoice proof copy (電子發票證明聯). A copy issued to a business also shows the buyer’s tax ID.
Value Added Tax overview
Scope of taxation
Except for entities specifically designated as non-VAT, all business entities fall within the scope of the VAT system. VAT is charged on the value added to goods or services at each stage in the production and distribution chain.
VAT rate: 5%
Refund of overpaid VAT
The amount of overpaid VAT claimed by a business entity will be refunded after verification by the tax authorities when:
- Overpaid VAT is on goods or services subject to zero-rated VAT (0% VAT).
- Overpaid VAT is on purchased fixed assets.
- Overpaid VAT arises when a business applies to cancel registration due to merger, transfer, dissolution, or cessation.
Overpaid VAT resulting from other circumstances may be offset against future business tax payable. Business entities with special situations can request approval from the MOF to receive tax refunds.
VAT calculation
Output VAT is the VAT a business collects from customers when selling goods or providing services. The taxable sales amount includes all compensation received — not just the product or service price, but also any expense reimbursements related to the transaction.
Input VAT is the VAT a business pays when purchasing goods or services. Input VAT can be deducted against output VAT, provided proper supporting documents are kept. Businesses must maintain:
- GUI invoices for purchases of goods and services
- GUI invoices for deemed sales of goods or services
- Other tax authority–approved documents specifying VAT amounts
If input VAT exceeds output VAT, the company records a VAT credit.
VAT exempt and zero-rated VAT
Exempt supplies are not subject to VAT, and input VAT cannot be reclaimed. Zero-rated supplies are taxed at 0% but still allow input VAT recovery. This distinction matters a great deal in practice.
Examples of VAT-exempt supplies
- Sale of land
- School textbooks approved by the Ministry of Education
- Newspapers, magazines, and broadcasting programs (excluding advertisements)
- Unprocessed agricultural, fishery, and livestock products
- Rice and flour sales, and rice milling services
- Fertilizers, agricultural machinery, and related supplies
- Gold bars, coins, and pure gold jewelry
Examples of zero-rated supplies
- Exported goods
- Services provided in Taiwan but used abroad (export services)
- Duty-free shop sales to outbound travelers
- Goods and services sold to bonded zones or free trade areas for export
- International transportation by qualifying foreign carriers
- Sales and repairs of international transport vessels and aircraft
VAT filing
- VAT returns must be filed every two months.
- The deadline is the 15th of the month following the reporting period.
- Example: for sales in January–February, the VAT return and payment are due by March 15.
Non-deductible VAT
Not all GUIs can be used to deduct VAT. The following are non-deductible:
- Goods or services purchased that are not for the use of principal and ancillary business operations.
- Goods or services for social relations purposes. Business meals, travel expenses, and accommodation expenses are also not VAT-deductible.
- Goods or services rewarded to individual employees. Employee benefits, gifts to employees, and staff catering are not VAT-deductible.
- Passenger cars for personal use, except for business trucks.
- Invoices from other countries.
- Receipts, rent, and salary — because there is no VAT paid.
Invoicing requirements
To comply with Taiwan VAT rules and avoid penalties, all invoices must meet GUI requirements. Customers receiving incorrect GUIs may face difficulties when reclaiming VAT. A valid GUI must include:
- Date of issue
- Pre-printed sequential GUI number
- Seller’s VAT ID number
- Buyer’s VAT ID number
- Full name of both companies
- The product name, quantity, and price of the goods and services
Frequently asked questions
What is within the scope of VAT (business tax) in Taiwan?
- Sales of goods or services in Taiwan, including services bought from abroad but provided or used in Taiwan.
- Imports of goods into Taiwan.
What should we do if a customer returns goods after the GUI has been issued?
For an e-invoice (most GUIs today), the seller issues an electronic sales return / allowance certificate (銷貨退回、進貨退出或折讓證明單) and uploads it to the Ministry of Finance e-invoice platform. Since 1 January 2025 this is the seller’s responsibility, and the upload is due within 7 days if the buyer is a business, or within 2 days if the buyer is a consumer. For a paper GUI, if the sale has not yet been reported, the seller takes back the buyer’s copies and voids the GUI; if it has already been reported, the seller must obtain a sales return / allowance certificate issued by the buyer. If the goods are exchanged, a new GUI is issued for the replacement goods.
What if we lose the deduction or receipt copy of a purchase GUI?
For an e-invoice there is no paper copy to lose: the invoice data can be retrieved from the Ministry of Finance e-invoice platform.
For a paper GUI, you can use either of the following in place of the lost copy, as your input VAT deduction document or accounting voucher:
- a photocopy of the seller’s retention copy, stamped by the seller to certify it; or
- a photocopy of the copy you still have (for example, the receipt copy if the deduction copy is lost), stamped by your own company.
Can input VAT be claimed in a later period if we missed it?
Yes. Input VAT documents not reported in the period of the transaction may be reported in the next period. If they are still not reported in the next period, you can report them in a later period with an explanation of the reason, but only within 10 years.
Can a company deduct input VAT on a passenger car with 9 seats or fewer?
Buying: No. Input VAT on a passenger car for the company’s own use cannot be deducted. For example, the VAT on a sedan or SUV bought for executives cannot be offset against output VAT.
Leasing: It depends on the lease. Under a 2022 Ministry of Finance ruling:
- If the lease is in substance an instalment purchase — for example, ownership passes to the company at the end of the lease, the company has a bargain purchase option, the lease term covers at least three-quarters of the car’s economic life, or the present value of the lease payments is at least 90% of the car’s fair value — the input VAT cannot be deducted.
- Otherwise, the input VAT can be deducted only if the car is used for the company’s business, its use is not restricted to employees above a certain level, and the company manages its cars centrally.
So a leased car reserved for a particular executive generally does not qualify.
What are the requirements for zero-rated VAT on export-related services?
The 0% rate applies to services related to exports, and to services provided in Taiwan but used abroad. Services provided to a foreign company but used in Taiwan do not qualify.
Keep evidence that the service is used abroad and that payment came from abroad — for example, the contract, inward remittance and foreign exchange records. The tax office may also ask for emails or other correspondence about the transaction. See Zero-rated VAT on exported services for details.
Are bonded goods entering a bonded zone directly from abroad treated as imports?
No. Bonded goods entering a bonded zone — such as a technology industrial park, science park, agricultural technology park or free trade zone, or a Customs-supervised bonded factory, bonded warehouse or logistics center — are not treated as imports. They become imports when they leave the bonded zone for other parts of Taiwan. See also Importing goods: VAT and documents.
If our company is dissolved and the remaining goods are used to pay debts or distributed to shareholders, is VAT due?
Yes. Goods remaining when a business is dissolved, and goods used to pay debts or distributed to shareholders or investors, are deemed sales of goods. The business must issue a GUI based on the market price and report and pay the VAT.
Is it a sale of goods if a company uses equipment to pay for new shares in another company?
Yes. Using equipment to pay for new shares in another company’s capital increase is a sale of goods. The sales amount is the higher of the market value of the equipment or of the new shares, and the business must issue a GUI to the company it invests in.
Should a GUI be issued for liquidated damages received in connection with a sale of goods or services?
Yes. Liquidated damages received by a business in connection with its sale of goods or services are part of the sales amount and are subject to VAT, so a GUI must be issued. The sales amount means the total consideration received for the sale, including all charges collected in addition to the price.
Example: Company A contracted with Company B for excavation work. Company B terminated the contract early and paid Company A NT$1 million in liquidated damages. The payment is part of the sales amount for the service, so Company A must issue a GUI and pay VAT on it.